

Bard Santner, a financial services group offering asset management, corporate finance, wealth management, and remittance services, is positioning itself to capture a larger share of Zimbabwe’s $2.45 billion diaspora market. Through its newly licenced deposit-taking microfinance bank, the firm is attempting a structural shift: moving beyond zero-margin transactional transfers into high-yield lending, wealth management, and deposit mobilisation.
The strategic core of this expansion is customer lifetime value. Pure-play remittance companies face severe price compression, but by bundling credit and savings onto existing cross-border flows, Bard Santner aims to convert transactional users into long-term banking clients. However, a large remittance corridor does not inherently guarantee adoption by banks, particularly given regulatory moats in South Africa and fierce competition from incumbent digital banks.
Bard Santner: From Remittances to Banking
The operational backdrop is defined by South Africa’s rapid surge in digital banking. A PwC analysis of major banks showed that digitally active clients rose to 27.6 million in the second half of 2025, up from 21 million in the first half. This shift has altered migrant banking habits, turning cross-border payments into an entry point for broader financial services.
Digital challengers like GoTyme Bank, Bank Zero, and Discovery Bank compete aggressively on transaction costs and yields, while remittance incumbents, including Mukuru, Mama Money, and Hello Paisa, maintain deep distribution networks across primary migrant corridors. Bard Santner’s entry relies on bridging these two distinct operational models.
This overlap highlights the real battleground: customer retention across borders. The key leverage point for a remittance-first bank is capital efficiency. A customer who regularly sends money to Zimbabwe represents lower customer acquisition costs for credit and savings products, provided the infrastructure can support seamless cross-border clearing.
For remittance providers, expanding into deposit-taking is a defensive necessity to combat margin compression. For traditional banks, cross-border integration remains a friction-heavy gap. To succeed, new entrants must offer clear interest differentials or direct credit access tied to historical transfer data.
The market’s sheer volume explains the incentive. Formal diaspora remittances reached $1.62 billion in the first seven months of 2026, up 24% year-on-year, according to data from the Reserve Bank of Zimbabwe. Yet gross inflow figures mask a structural problem: capital velocity remains strictly one-directional, with minimal retention in formal savings or investment vehicles.
Converting transactional flows into sticky deposits requires overcoming deep-seated distrust of currency and a strong preference for cash. Without compelling multi-currency protections or competitive credit yields, gross remittance volume will remain an unreliable indicator of potential banking assets under management.
Bard Santner’s cross-border ambition
Operating across Harare, Johannesburg, and New York, Bard Santner leverages its subsidiary, TX Money Transfer, as the primary funnel. Its proposed banking suite—encompassing multi-currency accounts, SME cross-border trade finance, and diaspora-linked credit—aims to monetise both ends of the transfer corridor simultaneously.
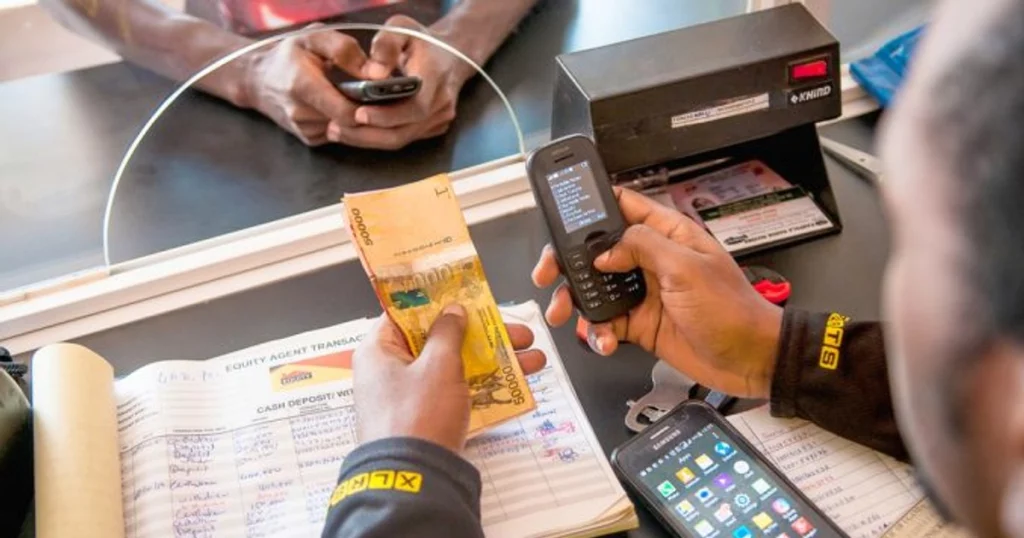
The group’s microfinance banking licence, granted by the Reserve Bank of Zimbabwe, took effect on October 1, 2026. While this provides the legal framework to take deposits and issue loans within Zimbabwe, it highlights the geographic limitation of single-jurisdiction licensing in a cross-border market.
The central thesis behind the strategy is serving migrants in both their host and origin economies, a positioning that larger regional banks struggle to execute efficiently due to legacy compliance and operating silos.
An existing remittance base gives Bard Santner an immediate distribution channel, but conversion metrics will be the real test. Without public data on active transaction users, retention rates, or loan default projections, the size of its immediate total addressable market remains unverified.
Regulatory test
Building a cross-border banking proposition also means navigating different regulatory systems.
Crucially, a Zimbabwean banking licence does not permit deposit-taking or credit underwriting in South Africa under South African Reserve Bank (SARB) regulations. Without local banking partnerships or a specialised license, foreign institutions cannot natively hold South African Rand deposits.
This regulatory divide creates a potential bottleneck for a seamless cross-border proposition. Bard Santner must maintain clear operational separation between South African remittance origination and Zimbabwean banking execution, or face significant regulatory exposure under exchange control frameworks.
It must also compete on measurable factors, including transfer fees, exchange rates, processing times and service reliability. Differences in fees and exchange rates can affect how much recipients receive, making transparent pricing important to customers sending money home.
Savings and lending introduce further requirements around capital, credit assessment, affordability and consumer protection. Multi-currency products also require clarity about exchange-rate exposure and the terms governing access to funds.
The key indicators to watch will be customer acquisition costs, net interest margins on multi-currency loans, capital adequacy ratios, and the formal structure of its South African partnership model. Demonstrating sustainable credit performance in a volatile macroeconomic environment will determine whether the bank can scale.
Zimbabwe’s diaspora remittances provide a substantial market, but the commercial opportunity lies in building broader financial relationships around those flows. Bard Santner’s challenge is to give customers clear reasons to use its services beyond sending money home, while competing with established providers and meeting the regulatory demands of operating across borders.
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.

from TechCabal https://ift.tt/0aAUPtk
via IFTTT

I am the CEO of 9JAGISTLAND.My name is Adedeji Timothy and my co-owner is Oyekola Damilare.This blog is born out of our passion to educating to people in all aspect of internet life.We are enthusiastic about writing posts and articles online.
Write your views on this post and share it. ConversionConversion EmoticonEmoticon